
Why get professional advice?
Many first-time investors opt for online DIY or “execution-only” services when setting up their investments. The marketing for these services can be persuasive, encouraging you to take responsibility for your financial future while avoiding the costs associated with professional financial advice.
But these services have their limits. When it comes to something as important as building your investment pot - whether for your retirement, to pay your children’s university costs, or simply for a rainy day - getting help from a professional can make a significant difference.
The Week
Escape your echo chamber. Get the facts behind the news, plus analysis from multiple perspectives.

Sign up for The Week's Free Newsletters
Join more than 350,000 subscribers and keep yourself informed with a selection of The Week’s most interesting, enlightening and entertaining stories - plus daily puzzles.
Join more than 350,000 subscribers and keep yourself informed with a selection of The Week’s most interesting, enlightening and entertaining stories - plus daily puzzles.
One key way in which a professional adviser can provide better value than a DIY service is by assessing your risk profile. If your money is in a portfolio that is more risky than you are comfortable with, you could end up sweating as its value swings. Worse yet, you could wind up not meeting your investment objectives, because you either took on too much or too little risk.
For example, if you were asked where on a scale of one to five you sat in terms of how much investment risk you are comfortable taking on, chances are you would put yourself at a three. This is because most people, especially those with little experience in investing, tend to lack a clear conception of what constitutes a risky investment. Most tend to think of themselves as moderate risk-takers.
Almost nobody will put themselves at either extreme on the risk scale, even if a professional might recognise that they were very risk-averse, or risk-tolerant. Execution-only services can initially appear to be cheaper. But paying a professional adviser from Charles Stanley to manage your portfolio can save you money in the long term, by helping you keep costs down and avoid hidden fees and unnecessary risks.
How can risk assessment help?
Clearly, it is extremely difficult for an individual with little or no experience in investing to correctly assess how much risk they are comfortable taking and what that means in terms of how and where they should invest their money.
A professional risk assessment, usually delivered via a risk profiling tool and/or a qualified investment adviser, will help you decide whether you can afford to take on more risk, to target higher returns, or should consider dialling down your risk level in order to make a more defensive portfolio.
A professional risk management service such as that employed by Charles Stanley’s Personal Portfolio Service will pinpoint precisely how much risk you should be taking. It will consider both practical and emotional factors: how much could you afford to lose before your quality of life would be affected? How comfortable are you about your investments potentially fluctuating in value by 10% in a single year, or 15%, or more? Once you’ve answered their questions, a professional investment manager, or relationship manager, will invest your money in a fund, model portfolio or bespoke portfolio that is best suited to your objectives, timelines and of course, attitude to risk.
Among other things, your attitude to risk will be reflected in the asset composition of your investment portfolio. Different assets carry different amounts of risk. For example, shares have typically been seen as the riskiest type of asset, while government bonds have generally been perceived as less risky. Of course, it’s impossible to take all the risk out of investing, but professionals can manage the make-up of their clients’ investments - be it in one of a set of risk-rated funds, or an entirely custom-built portfolio - in order to reduce the chance of unpleasant surprises.
Looking to the future
When you invest your money with Charles Stanley’s Personal Portfolio Service, your attitude to risk is reassessed every year to ensure that the way your money is invested is still right for you as your life circumstances and priorities change. Life’s changing priorities and ups and downs make an ongoing assessment of your attitude to risk a sensible choice for anyone investing over time. No more fiddling or worrying: you can just relax, secure in the knowledge that your money is in the best possible hands – those of an actual human being whose job is to analyse and manage risk.
Find out more at Charles-stanley.co.uk/personal-portfolio-service
The value of investments can go down as well as up and investors may not get back the amount they originally invested.
Charles Stanley & Co. Limited is authorised and regulated by the Financial Conduct Authority and a member of the London Stock Exchange. Registered in England No. 1903304, Registered office: 55 Bishopsgate, London EC2N 3AS.
-
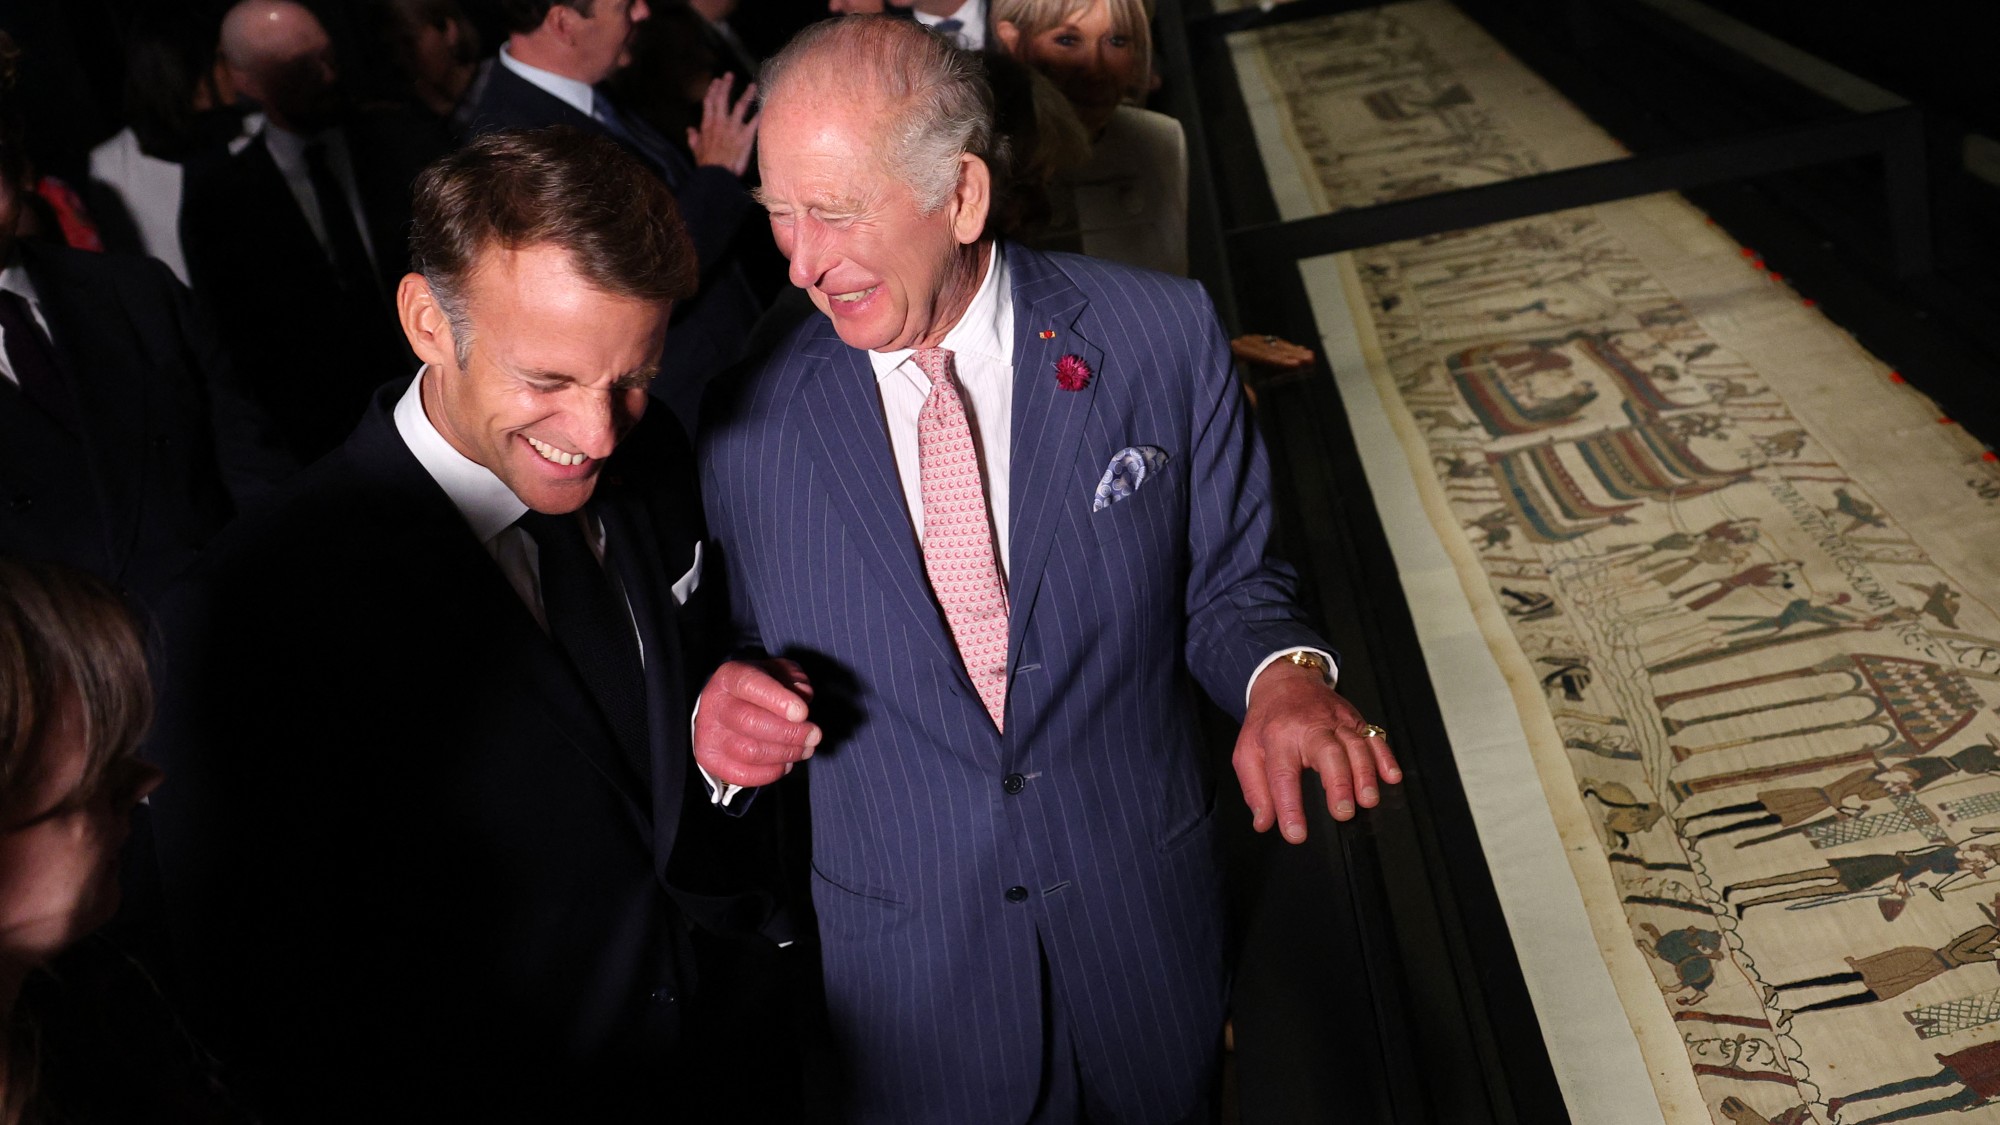 Why the Bayeux Tapestry is one in the eye for commoners
Tech billionaires and art critics can take their time enjoying the 11th-century relic in London. But the public must hurry along
-
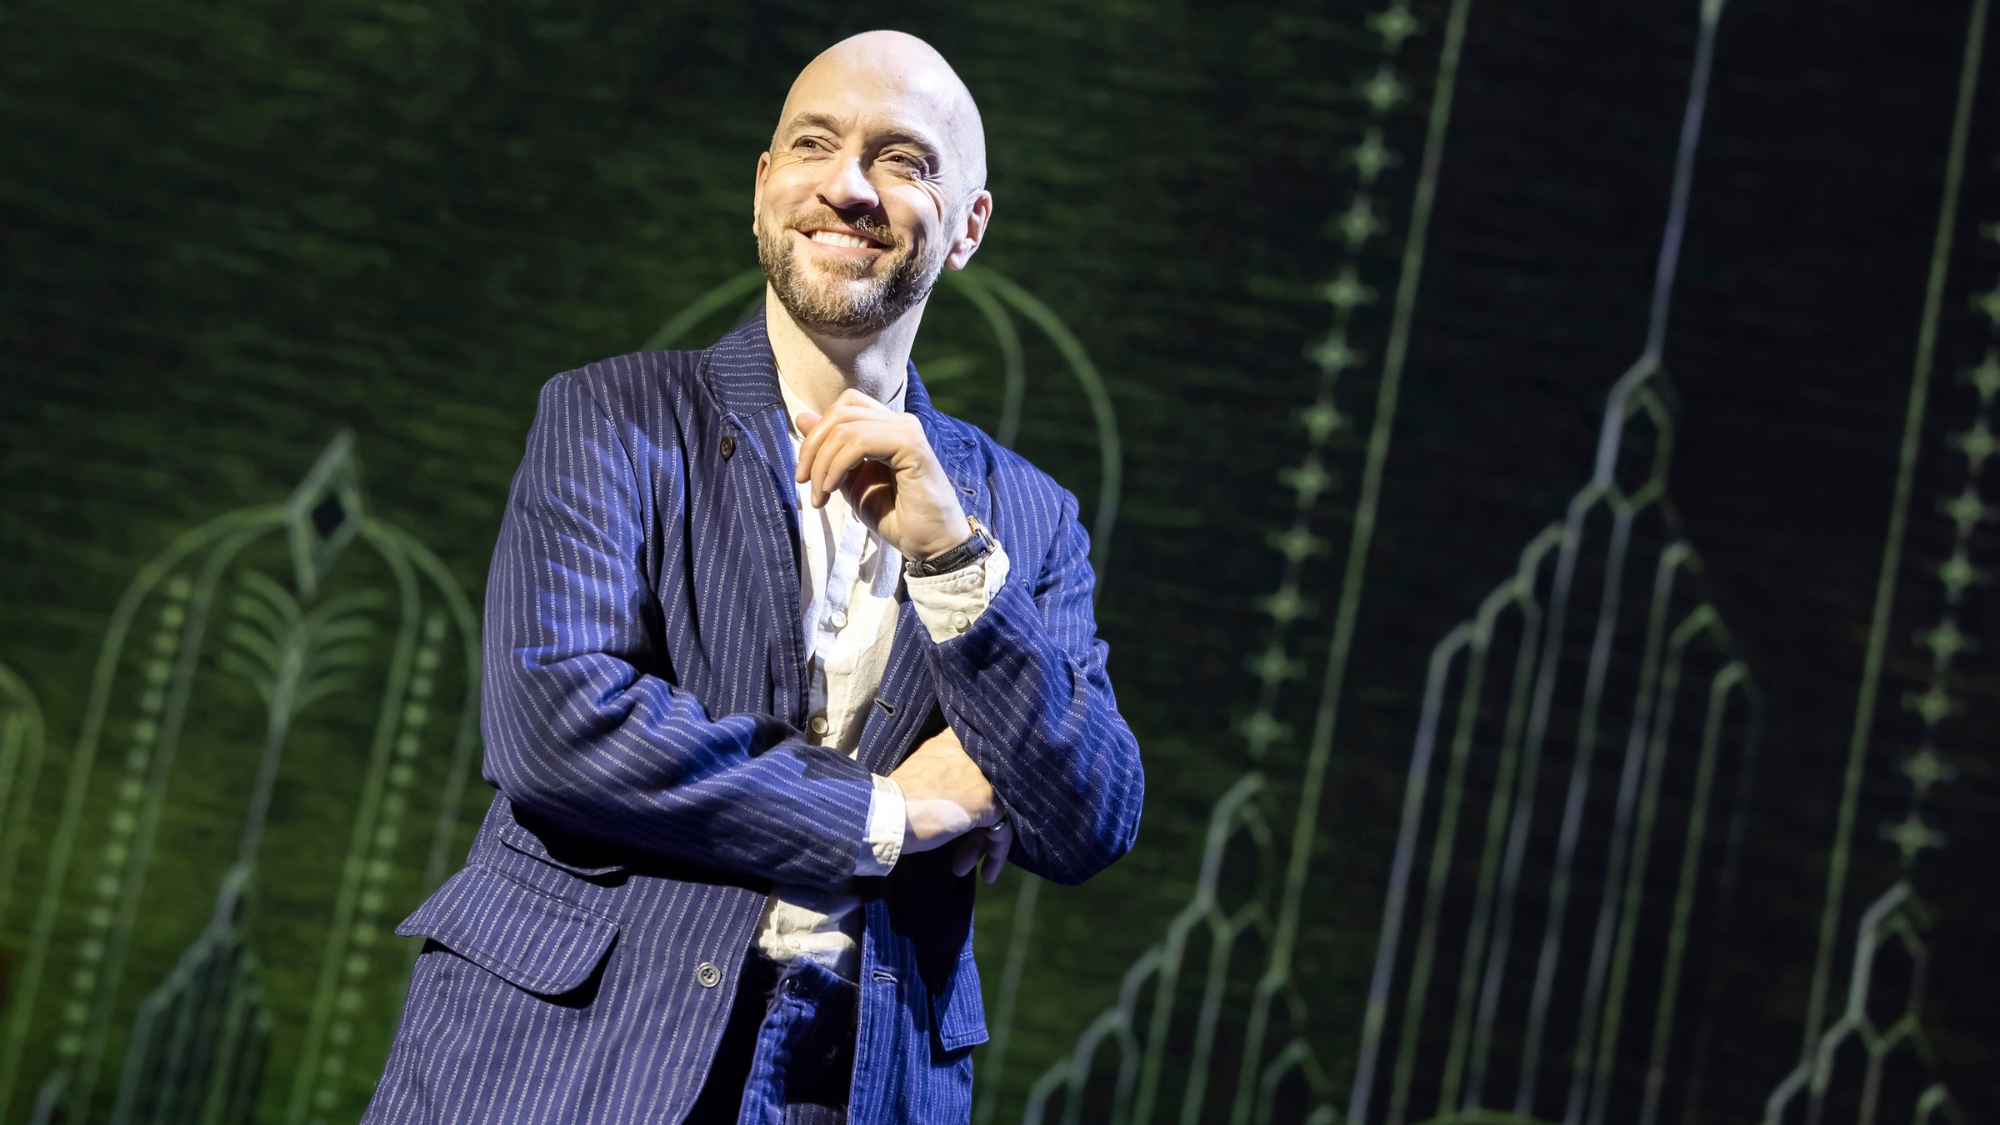 Derren Brown: Only Human – a ‘mind-warping’ show
The Week Recommends The illusionist’s latest West End offering features ‘one gasp-inducing stunt after another’
-
 Donald Trump, Venezuelan oil, and ‘the 51st state’
The Explainer As first barrel of Venezuelan crude arrives in the US, controversial oil deal with Caracas is seen by many as US asset seizure


-
 You missed a credit card payment. Now what?
The Explainer Time is of the essence
-
 Where are mortgage rates heading in 2027?
The Explainer There is one clear direction: up
-
 How can you lock in a mortgage rate and when does it make sense to do?
The Explainer If rates are likely to go up between when you apply and when you close, you may want to consider a lock
-
 What to know before using a 0% interest credit card
The Explainer Is there a catch?
-
 What to consider when choosing a brokerage account
the explainer Find one that properly supports your investing goals
-
 Are home warranties worthwhile?
the explainer Even the most careful homeowner will experience damage to an appliance or major system eventually
-
 3 tips to finally build up an emergency fund
The Explainer Hope for the best, but prepare for the worst
-
 How can home sellers navigate high mortgage rates?
the explainer The housing market is giving buyers more negotiating power


